Most pitches we see describe what the buyer will do to improve the business after closing. A small percentage of sponsors take the opposite approach: they begin building parts of the value creation plan before they raise capital.
In roughly 3% of the deals we evaluated this past year, the sponsor had started building and operating part of the platform strategy before asking for acquisition equity. In our experience it changes the conversation quite a bit, because the value creation plan becomes something an investor can actually diligence rather than something that requires imagination.
Four versions we've seen
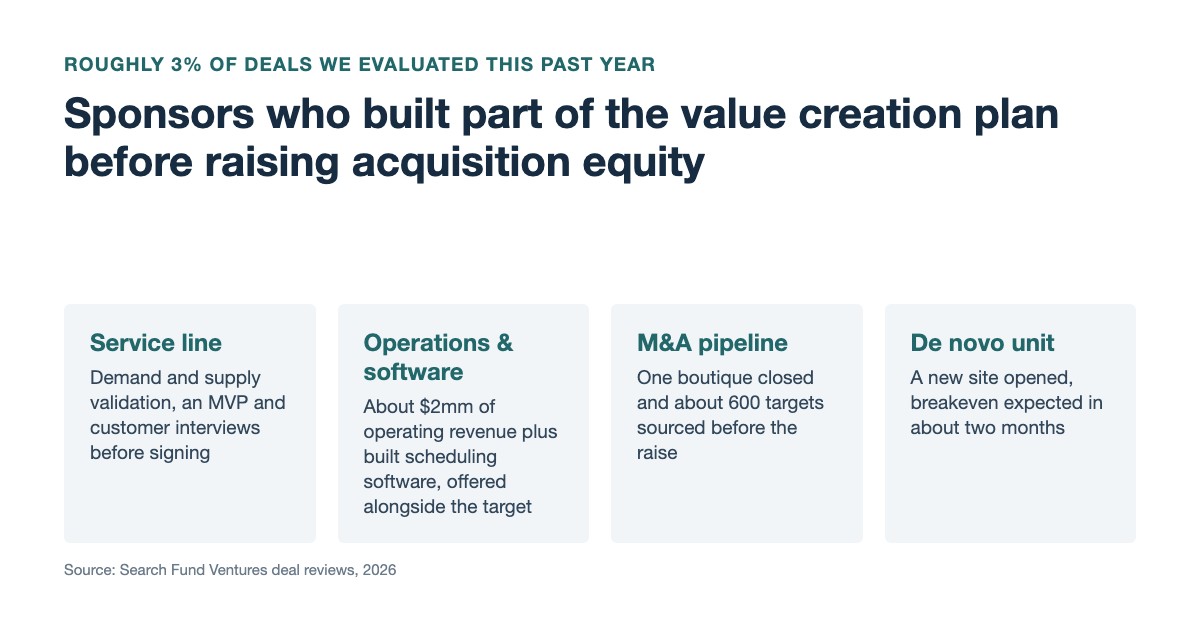
A service line. One sponsor we backed this year designed a new offering before signing the platform deal. They arrived with demand and supply validation work, a product MVP and voice of the customer work. The target's own churn data then showed that more than half of departing clients had left for reasons the new line could address. The round was oversubscribed.
Existing operations and software. A home care sponsor proposed rolling roughly $2mm of revenue it already operates, plus scheduling software it had already built, into the agency it had under LOI. Investors weren't being asked to believe the sponsor could run home care operations or build the software. Both already existed.
A real M&A pipeline. Two founders of a professional services rollup closed one boutique deal at about 1x EBITDA of cash up front. They also built a sourcing engine from public data that produced about 600 targets, with multiple bolt-ons under LOI during the platform equity raise. The add-on strategy came with a working pipeline, not a slide.
A de novo unit. A behavioral health operator opened a new site and expected breakeven within about two months. Opening new sites was a key part of the value creation plan, and the sponsor had already shown they could do it.